-
by sayum
10 October 2026 8:11 AM







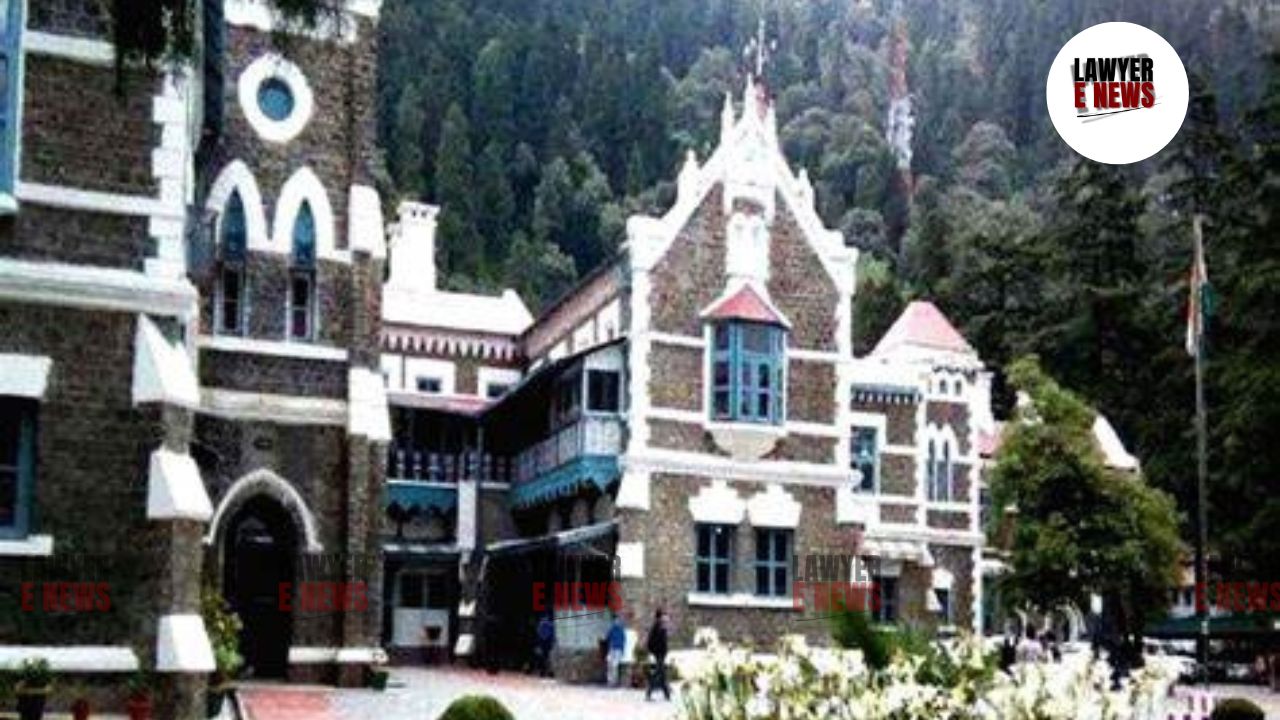
"The legislative competence of the State has to be tested by reference to the substance and incidence of the levy, and not merely by reference to the ultimate use to which the goods may substantially be put." Uttarakhand High Court, in a significant ruling, held that the State Legislature lacks the constitutional competence to levy development cess on agricultural produce brought from outside the State solely for manufacturing or processing, where no sale or purchase occurs within the market area.
A bench of Chief Justice Manoj Kumar Gupta and Justice Subhash Upadhyay observed that such an impost cannot be sustained under Entry 28 or Entry 66 of List II of the Seventh Schedule.
The petitioners, manufacturers operating in Uttarakhand, challenged the constitutional validity of the first proviso to Section 27(c)(v) of the Uttarakhand Agricultural Produce Marketing (Development and Regulation) Act, 2011. They contended that the provision improperly imposed a development cess on the mere entry of raw agricultural materials into the market area for industrial processing. The State had defended the levy, arguing that such "Secondary Arrivals" used market infrastructure, thereby justifying the cess.
The primary question before the Court was whether the State Legislature possesses the competence to impose development cess on agricultural produce brought into a market area for manufacturing in the absence of any sale or purchase transaction. The Court also had to determine whether the ratio in the Supreme Court judgment of M/s Gujarat Ambuja Exports Ltd. vs. State of Uttarakhand (2016) regarding Section 27(c)(iii) applied to the impugned proviso of Section 27(c)(v).
Legislative Competence and the 'Gujarat Ambuja' Precedent
The Court noted that the Supreme Court in Gujarat Ambuja held that market legislation is fundamentally designed to regulate buyer-seller relationships and ensure fair returns to producers. By striking down Section 27(c)(iii), the Supreme Court clarified that taxing the mere import of goods for manufacturing, absent a market transaction, exceeds the State's legislative field.
"The Supreme Court held that the State Legislature lacked competence to impose market fee and development cess upon agricultural produce brought into the market area not for sale but merely for manufacturing or further processing."
Applicability to Section 27(c)(v) Proviso
The Bench rejected the State's contention that Section 27(c)(v) could be distinguished from the invalidated Section 27(c)(iii) simply because it labeled the event as "Other Secondary Arrival" or sought only "development cess" rather than "market fee."
Court Rejects Attempt to Circumvent Precedent
The Court emphasized that the constitutional infirmity was not dependent on the nomenclature of the impost or the labeling of the transaction. The substance of the transaction—moving goods for manufacture without a sale—remains the same, regardless of the classification used in the statute.
"The ratio of Gujarat Ambuja cannot be circumvented by shifting substantially the same levy from one sub-clause to another, by describing the movement of goods as ‘Primary Arrival’ or ‘Additional Secondary Arrival’, or by retaining development cess while excluding market fee."
Infrastructure Argument Dismissed
Regarding the State's argument that manufacturing units benefit from infrastructure like roads and bridges, the Court held that the utility of an amount collected cannot confer legislative competence. If the charging event itself does not fall within the scope of the State's legislative power under the Seventh Schedule, the purpose of the expenditure is irrelevant to the validity of the tax.
"The purpose for which the proceeds of a levy are utilized is distinct from the source of legislative power to impose the levy."
The High Court held that the first proviso to Section 27(c)(v) is beyond the legislative competence of the State Legislature. Consequently, the impugned notices and demands for development cess on the said basis were quashed. However, the Court clarified that this judgment does not preclude the levy of fees where a valid taxable transaction, such as an actual sale or purchase within a market area, is independently satisfied.
Date of Decision: 30 September 2026