-
by sayum
20 September 2026 7:34 AM







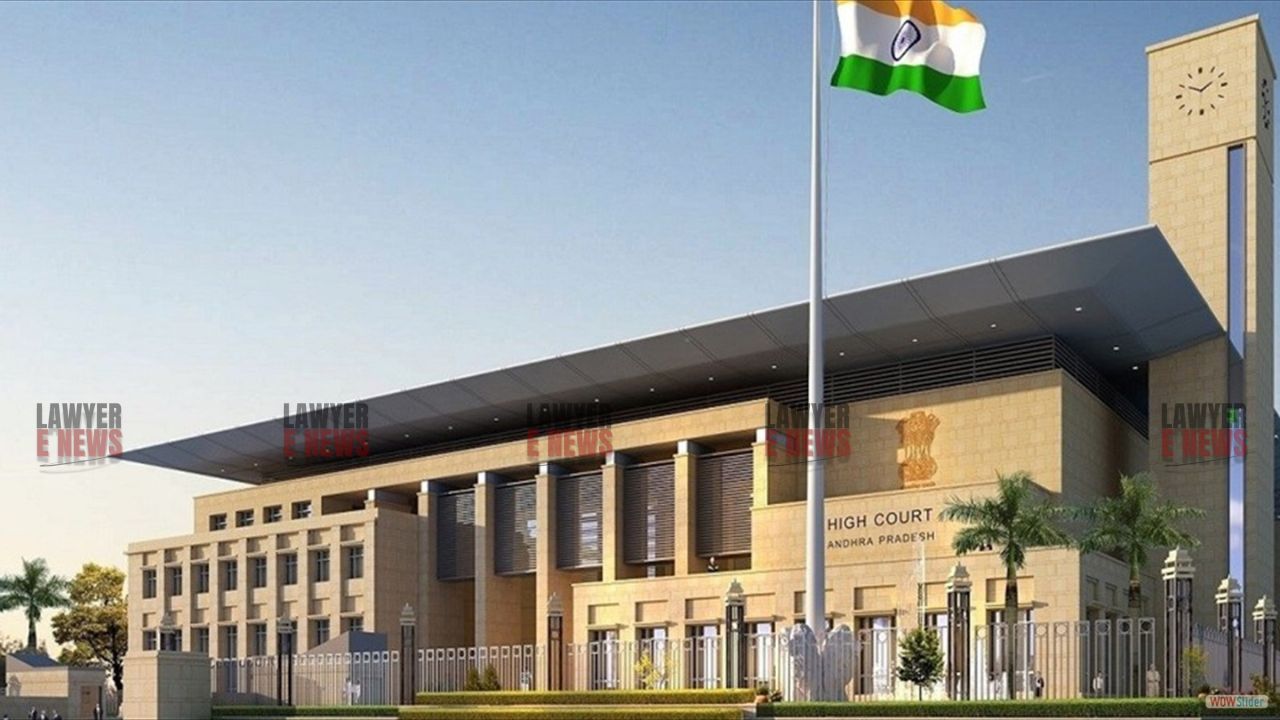
"When it is mandatory or obligatory on the part of the Banks to follow the Instructions/Directions issued with regard to the Framework for Revival and Rehabilitation of MSMEs, it would be equally incumbent on the part of the concerned MSMEs to be vigilant enough to follow the process laid down." Andhra Pradesh High Court, in a judgment dated September 3, 2026, held that MSME borrowers cannot seek the benefit of the 'Framework for Revival and Rehabilitation' after their loan accounts have already been classified as Non-Performing Assets (NPA) and recovery proceedings under the SARFAESI Act, 2002 have been initiated.
A bench of Justice Ravi Cheemalapati observed that the statutory guidelines for MSME revival mandate a proactive approach from the borrower, failing which they cannot invoke these protections at a belated stage to thwart recovery.
The petitioners, registered MSME firms, contended that despite their requests for loan restructuring due to COVID-19 related financial distress, the respondent bank declared their accounts as NPA without issuing a caution notice. They argued that the bank had violated the mandatory Master Directions issued by the Reserve Bank of India (RBI) regarding the 'Framework for Revival and Rehabilitation of MSMEs' notified under the MSMED Act, 2006.
Legal Framework for MSME Revival
The core legal question before the court was whether a borrower could claim the benefit of the MSME revival framework after the initiation of recovery proceedings under the SARFAESI Act, 2002. The court also examined whether the RBI's Master Directions of 2016 carry mandatory statutory force requiring banks to adopt a committee approach before declaring an account as NPA.
Court Explains Mandatory Nature of RBI Guidelines
The court reiterated that the RBI Master Directions, issued under Sections 21 and 35A of the Banking Regulation Act, 1949, are binding on all scheduled commercial banks. These directions require banks to identify incipient stress in MSME accounts by creating Special Mention Account (SMA) categories and adopting a committee approach for corrective action plans before an account is classified as an NPA.
"The instructions for the Framework for Revival and Rehabilitation of MSMEs... having statutory force, are binding to all Scheduled Commercial Banks," the court noted. The bench emphasized that these directions act as a supplement to the Banking Regulation Act and must be strictly adhered to by financial institutions.
Requirement of Vigilance from MSME Borrowers
While acknowledging the protective nature of the revival framework, the court underscored that the responsibility is reciprocal. Relying on the Supreme Court’s ruling in Pro Knits v. Board of Directors of Canara Bank, the court clarified that if a borrower fails to notify the bank of their MSME status at the appropriate stage or fails to invoke the framework before the account is declared an NPA, they cannot subsequently use the MSME plea to stall SARFAESI proceedings.
"If such an Enterprise allows the entire process for enforcement of security interest to be over, or having challenged such action in court and failed, such an Enterprise could not be permitted to misuse the process of law," the court observed.
No Relief at a Belated Stage
In the present case, the court noted that the petitioners failed to demonstrate that they had made a timely attempt to invoke the revival framework before their accounts were declared NPAs. Furthermore, because the bank had already proceeded to sell certain properties and third-party interests had already been created, the court found the petitioners' claims unsustainable.
Consequently, the writ petitions were dismissed, with the court concluding that the legal safeguards provided for MSMEs are not intended to be used as a tool to defeat recovery proceedings initiated after a borrower has failed to show timely vigilance.
Date of Decision: 03 September 2026