-
by sayum
06 November 2026 3:50 PM


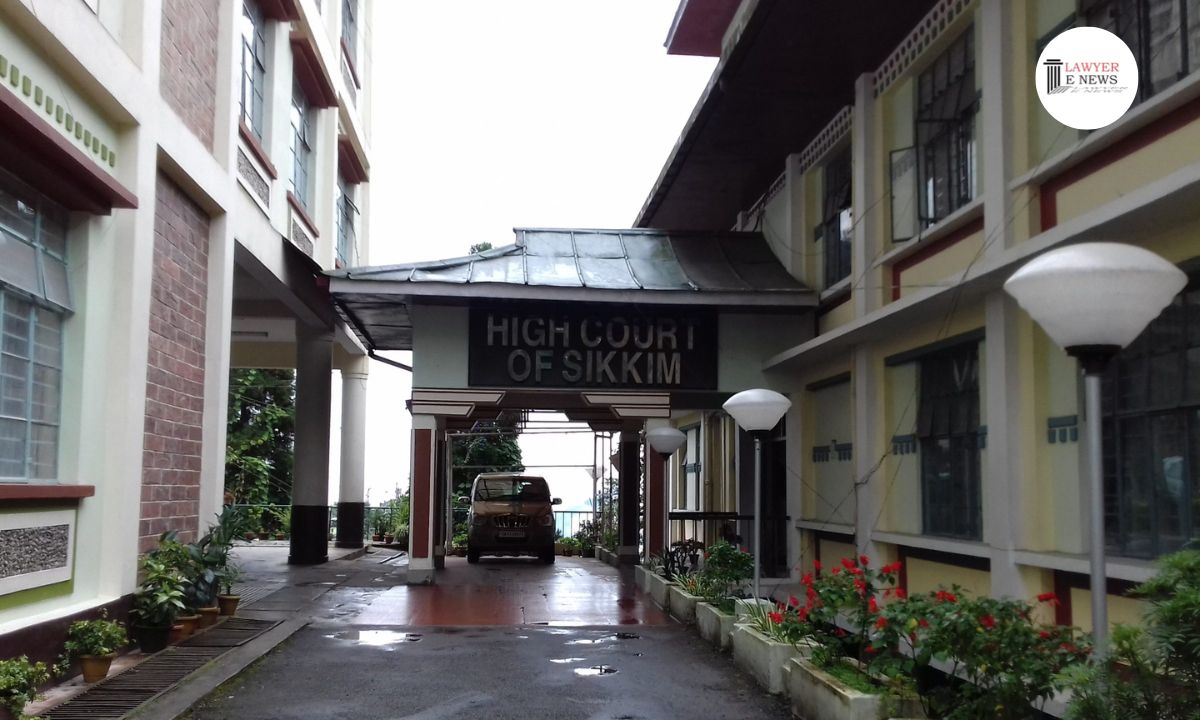
"The language used in section 149(1)(b) clearly contemplates new evidence and not new opinion. Merely because that opinion is written down in a document, it cannot be termed as new evidence entitling the Assessing Officer to revisit and reassess the assessment proceeding already completed." High Court of Sikkim, in a significant ruling dated October 14, 2026, held that an audit objection raised by the Comptroller and Auditor General of India, while constituting "information" under Explanation 1 to Section 148 of the Income Tax Act, 1961, cannot qualify as "books of account or other documents or evidence" under Section 149(1)(b) to reopen an assessment beyond the three-year limitation period.
A single bench of Justice Bhaskar Raj Pradhan observed that reopening an assessment solely on an audit memo amounts to an impermissible review and change of opinion, emphasizing that "the mandate of section 149(1)(b) is that no notice can be issued under section 148 unless the Assessing Officer has in his possession books of account or other documents or evidence which reveal that income chargeable to tax... has escaped assessment."
The petitioner, Zydus Healthcare Limited, challenged reassessment notices issued under Section 148 and orders under Section 148A(d) of the Income Tax Act for Assessment Years 2015-16, 2017-18, and 2018-19, which were initiated after the expiry of three years from the end of the relevant assessment years. The original scrutiny assessments under Section 143(3) had accepted the petitioner's returns claiming excise duty refunds as capital receipts and depreciation on goodwill arising from amalgamation schemes. The Revenue sought to reopen the proceedings based entirely on audit party objections issued by the Director General of Audit (Central), Kolkata, which flagged undercharge of tax.
The primary legal question before the court was whether an audit objection constitutes "books of account or other documents or evidence" in the possession of the Assessing Officer under Section 149(1)(b) so as to confer jurisdiction to issue a reassessment notice under Section 148 after the expiry of three years. The court was also called upon to determine whether the Revenue could initiate reassessment proceedings on concluded issues without any new tangible material, amounting to a change of opinion.
Writ Petition Maintainable Against Jurisdictional Defect Despite Alternative Remedy
Addressing the preliminary objections raised by the Revenue, the court reiterated that the existence of an alternative statutory remedy under Section 246A does not bar the High Court from exercising writ jurisdiction under Article 226 of the Constitution when the very jurisdiction of the Assessing Officer to reopen assessment is impugned. The court observed that the petitioner established the notices were issued without jurisdiction, rendering any subsequent orders non est.
The court rejected the Revenue's submission that passing a final reassessment order during the pendency of the writ petition rendered the challenge infructuous. Justice Pradhan held that if the foundational notice under Section 148 is invalid and without jurisdiction, all consequential proceedings inevitably collapse.
Passing Of Consequential Assessment Order Does Not Extinguish Jurisdictional Challenge
The bench pointed out that adjudication of proceedings during the pendency of the writ petition cannot extinguish the petitioner's core grievance against patent lack of jurisdiction. The court observed that if the notice under Section 148 is held to be without jurisdiction, then consequently the subsequent assessment order must also be held to be without jurisdiction.
"If the notice under section 148 is held to be without jurisdiction then consequently the subsequent assessment order must also be held to be without jurisdiction."
Mandatory Precondition Under Section 149(1)(b) Requires Tangible Possession Of Documents Or Evidence
Analyzing the scheme of Sections 147, 148, 148A, and 149 as substituted by the Finance Act, 2021 and amended by the Finance Act, 2022, the court emphasized that Section 149(1)(a) imposes a general bar against issuing notices under Section 148 after three years from the end of the relevant assessment year, unless the case squarely satisfies Section 149(1)(b). To invoke the extended window of up to ten years, the Assessing Officer must have in possession books of account, documents, or evidence revealing escapement of income representing an asset, expenditure, or book entry amounting to fifty lakh rupees or more.
The bench stressed that this statutory requirement places an affirmative burden on the Assessing Officer to explicitly state and reveal such possession in the order passed under Section 148A(d). The court observed that failure to do so completely disentitles the Revenue from reassessing under Section 148, as reassessment is an extraordinary power and not a plenary power of review.
Audit Memo Is Merely A Post-Facto Opinion, Not Independent Documentary Evidence
While Explanation 1(ii) to Section 148 clarifies that an audit objection raised by the Comptroller and Auditor General of India qualifies as "information" for Section 148 and Section 148A, the court clarified that such "information" does not automatically convert into "books of account or other documents or evidence" under Section 149(1)(b). The court held that an audit objection is merely a contrary opinion expressed by an external authority revisiting facts already on record.
Justice Pradhan ruled that the language of Section 149(1)(b) strictly demands new evidence and not a new opinion written down on paper. When an audit objection is flagged, the Assessing Officer must apply an independent mind and uncover actual books of account or documentary evidence establishing escapement before invoking the extended limitation period.
"Merely because the Explanation to section 148 recognises audit objection as 'information', it does not automatically qualify as 'books of account or other documents or evidence'."
Reopening On Existing Material Amounts To Impermissible Change Of Opinion
Relying on the Supreme Court's landmark decision in Commissioner of Income Tax v. Kelvinator of India Limited, the court held that the Assessing Officer cannot reopen completed scrutiny assessments on a mere change of opinion. The bench noted that all relevant details regarding the excise duty refund and goodwill amortization were furnished and scrutinized during the original assessments under Section 143(3).
The court referred with approval to the Gujarat High Court ruling in Songwon Speciality Chemicals India (P.) Ltd., upheld by the Supreme Court, and the Delhi High Court Division Bench decision in Sapphire Foods India Ltd. v. ACIT, which held that reassessment cannot be deployed as an instrument to review a concluded assessment merely because the audit party held a different legal view on disclosed facts.
Substantive Legal Claims On Excise Subsidies And Goodwill Fully Settled In Assessee's Favour
On merits, the court noted that the petitioner's treatment of the Central Excise duty refund as a capital receipt exempt from tax was backed by judicial precedents, including the Supreme Court's affirmation of the Jammu and Kashmir High Court's ruling in Commissioner of Income Tax v. Shree Balaji Alloys. Similarly, the claim of depreciation on goodwill arising out of amalgamation schemes was settled by the Supreme Court in CIT v. Smifs Securities Ltd., where goodwill was expressly recognized as an intangible asset under Section 32 of the Income Tax Act.
The court rejected the Revenue's argument that the original assessments were under Computer Assisted Scrutiny Selection (CASS) limited scrutiny, observing that the statutory bar under Section 149(1)(b) applies uniformly to all assessments and does not permit reopening beyond three years without fresh tangible evidentiary material.
The High Court allowed all three writ petitions, quashing the impugned notices issued under Section 148, the preceding orders under Section 148A(d), and all consequential reassessment proceedings and orders. The ruling establishes that the Revenue cannot reopen assessments beyond the three-year window under Section 149(1)(b) relying solely on CAG audit objections in the absence of independent tangible evidence.
Date of Decision: October 14, 2026