-
by sayum
08 October 2026 6:24 AM







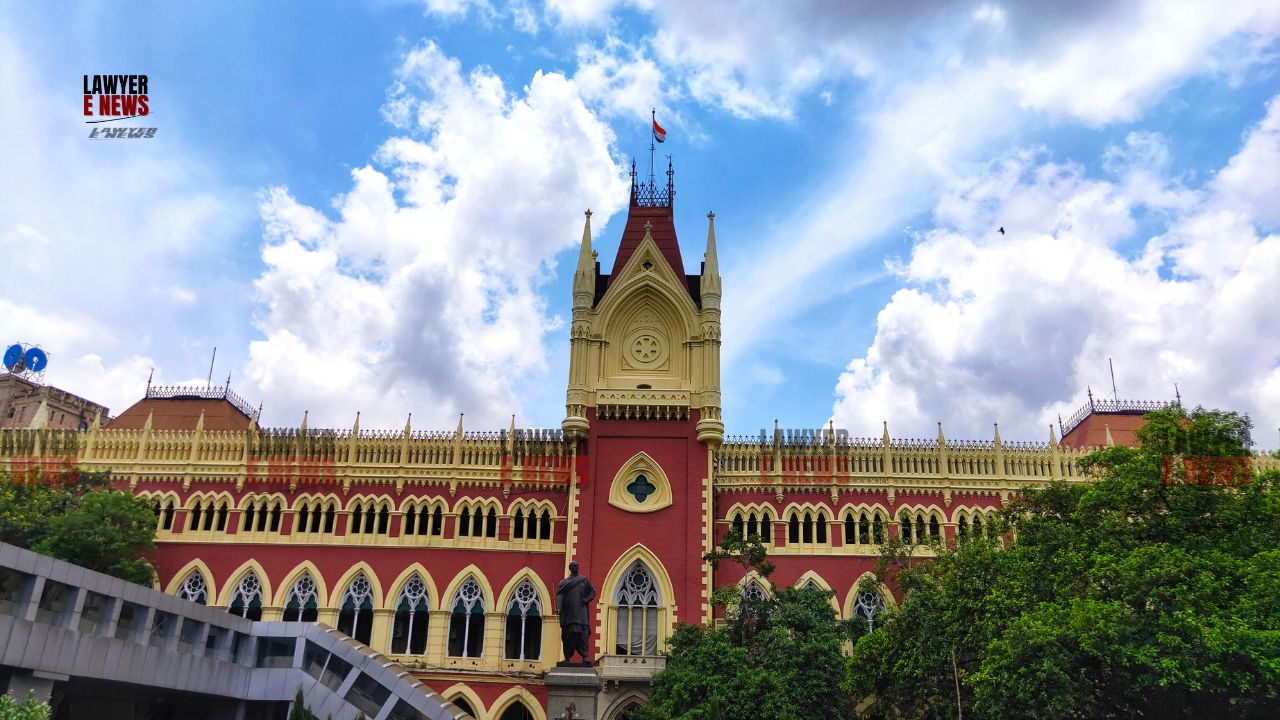
"The duty of full disclosure required that no information of substance or of interest to the insurer be omitted or concealed. Whether or not the insurer would have issued a life insurance cover despite the earlier cover of insurance is a decision which was required to be taken by the insurer after duly considering all relevant facts and circumstances." Calcutta High Court, in a ruling dated October 7, 2026, held that an insured person’s failure to disclose existing insurance policies in a proposal form constitutes a breach of the principle of uberrima fides (utmost good faith), thereby justifying the repudiation of an insurance claim.
Justice Krishna Rao, presiding over a writ petition, observed that when an insured provides inaccurate information—specifically by falsely declaring "zero" in response to a query regarding previous policy numbers—the insurer is well within its rights to avoid the contract.
The petitioner, Sayan Kundu, challenged an order by New India Assurance Company Limited, which had repudiated his late father’s insurance claims. The deceased had purchased four personal accident insurance policies, totaling a sum assured of Rs. 1 crore, while simultaneously holding other policies with different insurers. Following the father's accidental death in a railway incident, the respondent insurer discovered the existence of other policies and repudiated the claim on grounds of suppression of material facts and misrepresentation.
The core legal question was whether the insurer can validly repudiate an insurance policy when the insured has failed to disclose the existence of prior insurance coverage. The court also examined the impact of an insured affirmatively entering "0" (zero) in the "previous policy number" column of an electronic proposal form, as opposed to leaving it blank.
Nature of Insurance Contracts
The court emphasized that insurance contracts are governed by the principle of uberrima fides or "utmost good faith." Under the Indian Contract Act, 1872, any contract involving the concealment of material facts, misrepresentation, or fraud is rendered invalid. The bench noted that a complete and clear declaration of all material facts is a vital prerequisite for validating an insurance contract.
Distinguishing Between Blank and False Declarations
Addressing the petitioner’s reliance on Manmohan Nanda v. United India Assurance Company Limited, the court clarified that the ruling in Manmohan Nanda applies when a specific column in a proposal form is left blank, in which case the insurer is expected to seek clarification. However, in the present case, the insured had explicitly filled the column with "0," actively misleading the insurer.
Materiality of Disclosure
The court relied on Reliance Life Insurance Company Limited v. Rekhaben Nareshbhai Rathod, reiterating that any fact influencing a prudent insurer’s decision to accept a risk is "material." The disclosure of earlier insurance covers is essential for the insurer to assess why an individual is procuring multiple high-value policies within a short timeframe. Such information is vital for the insurer to evaluate the risk appetite and determine the terms of the cover.
Electronic Proposals and Transparency
The court observed that the transition to "e-proposals" via digital modes does not absolve the insured of the duty of disclosure. Under the IRDAI (Issuance of E-Insurance Policies) Regulations, 2016, electronic forms must capture all material information. Since the deceased had validated the proposal through an OTP, the court held that the declaration provided in the form was binding, and the entry of "0" constituted a deliberate suppression of material facts.
"The finding of a material misrepresentation or concealment in insurance has a significant effect upon both the insured and the insurer in the event of a dispute. The fact it would influence the decision of a prudent insurer in deciding as to whether or not to accept a risk is a material fact."
Application to the Present Facts
The court concluded that because the insured provided false information rather than leaving a query blank, the insurer was justified in viewing the contract as voidable. The failure to disclose existing coverage deprived the insurer of its right to assess the moral and financial risk associated with the applicant, thereby validating the repudiation of the claims. The writ petition was consequently dismissed, upholding the insurer's decision.
The Calcutta High Court’s decision reaffirms the high threshold of disclosure required in insurance contracts. By distinguishing between instances of incomplete forms and active misrepresentation, the court has provided clear guidance to policyholders: any attempt to misstate or conceal prior insurance coverage will be viewed as a fatal breach of the duty of utmost good faith, entitling the insurer to avoid its liability.
Date of Decision: 07 October 2026