Allegations In Matrimonial Disputes Must Be Specific And Supported By Foundation Facts To Avoid Abuse Of Process: Supreme Court Supreme Court Modifies Sentence To Period Already Undergone Citing Medical Condition And Expression Of Remorse Qualification Of '10+2 System' Cannot Be Equated With Other Certifications Absent An Equivalence Clause: Supreme Court Essential Qualifications In Recruitment Cannot Be Diluted Or Subject To Judicial Equivalence: Supreme Court Court Has Discretion To Decide Genuineness Of Signature By Comparison; Not Essential To Invoke Expert Opinion In All Cases: Supreme Court Civil Disputes Cannot Be Converted Into Criminal Offences To Recover Money: Supreme Court Quashes FIR Under Section 420 IPC Taxing Authorities Must Classify Goods Based On Form At Time Of Sale, Not End Use: Supreme Court Suit For Declaration Of Status Must Seek Consequential Relief To Avoid Bar Of Proviso: Allahabad High Court Illegal Detention | Police Failure To Maintain CCTV Footage Invokes Adverse Presumption Under Sec 119 BSA Against State: Allahabad High Court Section 138 NI Act | Accused Rebuts Presumption By Proving Intimation Of Misplaced Cheque To Bank And Lack Of Documentation For Alleged Settlement: Andhra Pradesh High Court Garnishee Proceedings Under CPC | Disputed Debt Cannot Be Summarily Adjudicated Without Leading Evidence: Bombay High Court Criminal Procedure (Identification) Act 2022 | Magistrate’s Power Under Section 5 To Direct DNA Profiling Is Not Conditional Upon Consent: Calcutta High Court Conviction Based On 'Assumption And Presumption' Cannot Be Sustained: Bombay High Court Acquits Husband Limitation Act | Suit For Specific Performance Must Be Filed Within Reasonable Time Even If No Date For Performance Is Fixed: Delhi High Court Enrolment As Advocate | Bar Council Must Consider 'Equivalent Qualifications' Under Rule 4(a) Rules Of Legal Education: Karnataka High Court Section 482 BNSS | Pre-Arrest Bail Is Not A Matter Of Course; Must Show Special Case For Invoking Extraordinary Jurisdiction: Kerala High Court Hindu Succession Act | A Co-parcener Cannot Alienate Entire Property; Non-Impleaded Legal Heir Not Bound By Previous Decree: Madras High Court Purchaser During Pendency Of Suit Bound By Compromise Decree, Cannot Treat It As Void In Collateral Proceedings: Punjab & Haryana High Court Order 23 Rule 1-A CPC | In Partition Suits, Defendants Asserting A Share Can Seek Transposition If Original Plaintiffs Withdraw: Patna High Court Section 69 BNS | Suppression Of Subsisting Marriage Or Live-In Relationship During Marriage Proposal Constitutes 'Deceitful Means': Kerala High Court Anticipatory Bail | Mere Apprehension Of Investigating Agency Is Insufficient To Deny Bail Without Demonstrating Necessity Of Custodial Interrogation: Telangana High Court Income Tax Evasion | Criminal Prosecution Under Section 276C IT Act Cannot Sustain Once Foundation Assessment Order Is Set Aside: Punjab & Haryana High Court

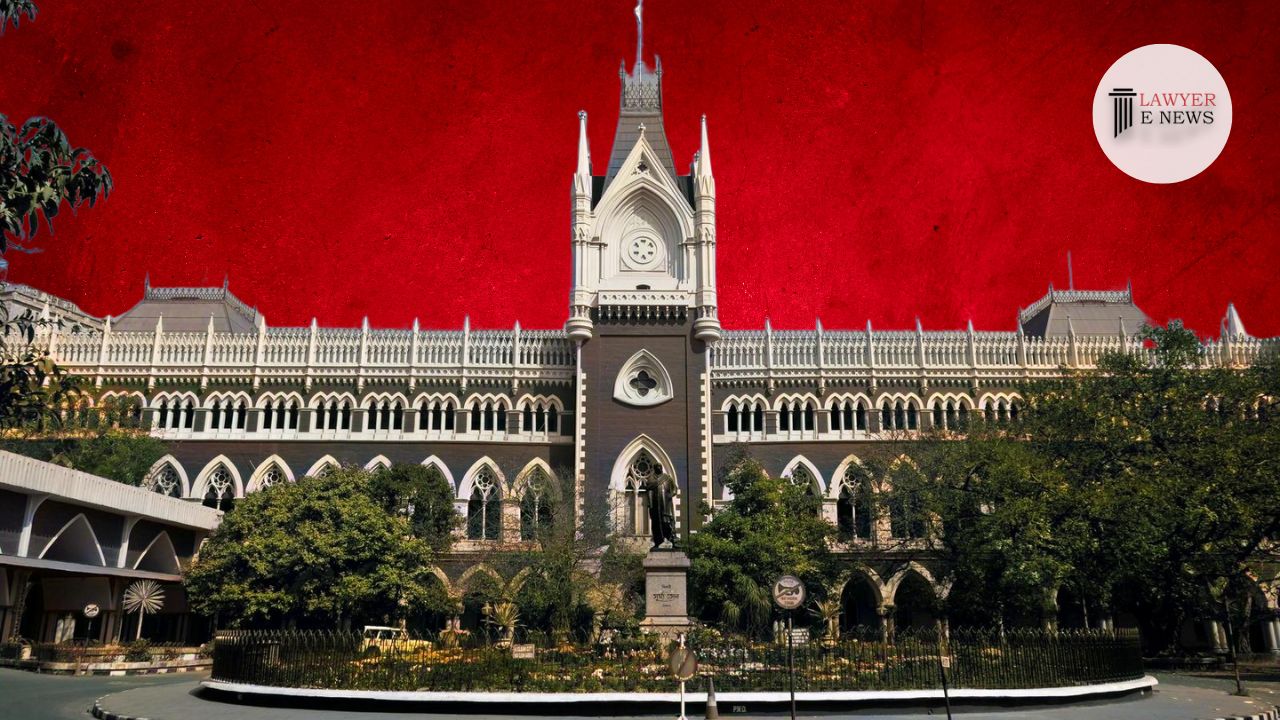
Procedural Violations in Issuance of Show-Cause Notice Cannot be Overlooked": Calcutta High Court Sets Aside Denial of Input Tax Credit to Lokenath Construction Pvt. Ltd.

07 May 2024 8:19 AM

By: Admin


In a significant ruling, the High Court of Calcutta has quashed both the show-cause notice and subsequent order denying Input Tax Credit (ITC) to Lokenath Construction Private Limited, citing procedural violations and jurisdictional errors by the West Bengal GST authorities.

Legal Point: The legal crux of the judgment revolves around the procedural propriety of the show-cause notice issued under Section 73(1) of the CGST/WBGST Act, 2017, and the rightful claim of Input Tax Credit under Section 16(2)(c) of the CGST Act, 2017. The court critically examined whether the denial of ITC was justified when procedural norms and jurisdictional mandates were not adhered to by the tax authorities.

The appeal arose from a show-cause notice dated August 22, 2023, issued by the WBGST Authorities, claiming that Lokenath Construction had availed ITC without proper evidence of tax payment by its suppliers. The contention of the appellant was that the show-cause notice was procedurally flawed as it did not verify facts from the supplier's end before denying the credit.

The court highlighted the procedural anomaly where the tax authority failed to verify the tax payment details from the supplier before issuing the show-cause notice. Citing the principle set in the Suncraft Energy Private Limited case, the court underscored that tax authorities must first proceed against the supplier in such cases.

The adjudicating authority’s decision to reject certificates from Chartered Accountants without seeking clarifications was criticized. The court pointed out that unilateral decisions without providing an opportunity to the assessee to clarify discrepancies were procedurally unjust.

It was observed that the findings of the adjudicating authority extended beyond the allegations in the show-cause notice, indicating a breach of the principles of natural justice.

The court applied precedents including the Suncraft Energy case and the Bharti Airtel Ltd. case, emphasizing that the taxpayer's right to ITC cannot be impeded without substantive evidence of collusion or fraud involving the taxpayer.

Decision: The High Court allowed the appeal, setting aside both the order dated December 28, 2023, and the initial show-cause notice. The court directed that the tax authorities first address any discrepancies with the supplier directly and only under exceptional circumstances, as outlined in relevant GST guidelines, should they proceed against the taxpayer.

Date of Decision: May 2, 2024

Lokenath Construction Private Limited v. Tax/Revenue Government of West Bengal and Others

Latest Legal News