-
by sayum
12 November 2026 10:35 AM


"Although the amount of premium, by itself, cannot enlarge the scope of contractual coverage, the insurer cannot be permitted to defeat the very object of the insurance by relying upon restrictive conditions unless it establishes that such conditions formed part of the contract and were duly communicated to the insured, " State Consumer Commission
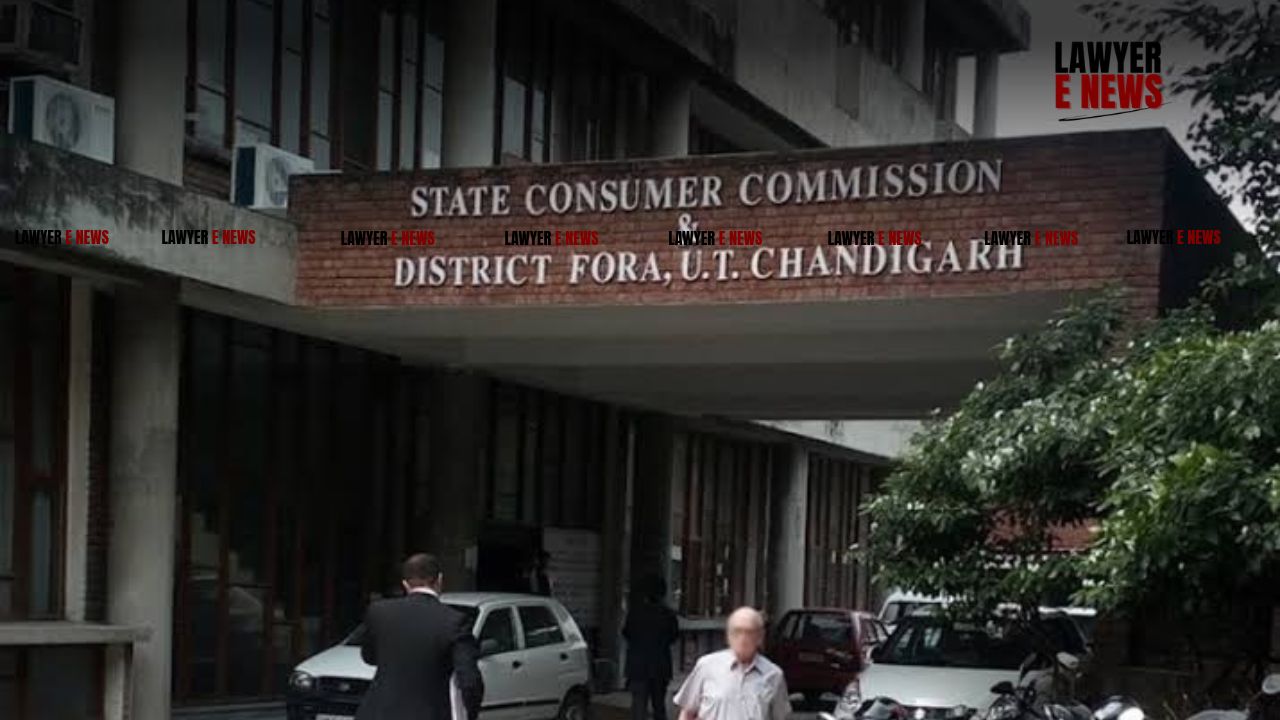
Chandigarh: Holding that an insurance company cannot repudiate a claim based on restrictive or exclusionary terms unless it produces cogent evidence demonstrating that such conditions were specifically communicated to and accepted by the policyholder, the State Consumer Disputes Redressal Commission, U.T., Chandigarh, comprising Presiding Member Padma Pandey and Member Rajesh K. Arya, on October 29, 2026, dismissed an appeal preferred by ICICI Lombard General Insurance Company Limited.
The complainant had obtained an insurance policy to secure his residential housing loan of ₹18 lakhs by paying a substantial premium of ₹1,37,000/-, on the assurance that the loan liability would be covered in the event of major illness, disability, or death. While working abroad, the complainant was diagnosed with multiple neurofibromatosis requiring major neurosurgical intervention with a grave risk of neurological deficit and paralysis, resulting in the loss of his livelihood. Upon approaching the insurer for loan liquidation under the policy, the insurer repudiated the claim on the ground that the ailment was not among the seven specifically enumerated diseases under the policy terms, prompting the District Commission to allow the complaint and order full reimbursement with interest.
Whether an insurer is legally entitled to repudiate an insurance claim on the basis of restrictive coverage clauses when it fails to prove that the detailed terms and conditions were ever supplied to, explained to, or accepted by the insured?
Whether an insurer who accepts a substantial premium without conducting an adequate pre-policy medical assessment can subsequently repudiate coverage for an incapacitating illness on hyper-technical exclusions under the Consumer Protection Act?
Addressing the severity of the insured's illness, the State Commission noted that the medical evidence, including clinical records from PGIMER Chandigarh, confirmed the existence of multiple lesions requiring extensive neurosurgical procedures carrying imminent risks of motor paralysis. The Commission observed that the disease was neither ordinary nor inconsequential and directly impaired the complainant's earning capacity, compelling him to leave his employment abroad.
Gravity of incapacitating illness and occupational disruption established legitimate expectation of policy coverage
The Bench underscored that the insurer's attempt to restrict coverage strictly to the seven illnesses specified under Section (i) of the policy booklet could not be accepted in the absence of proof of service of the policy wording. The Commission highlighted that the insurer failed to produce any signed proposal, declaration, or postal delivery acknowledgment establishing that the restrictive policy schedule was ever provided to the complainant at the inception of the contract.
Exclusionary terms cannot be invoked mechanically without proving prior disclosure and acceptance by insured
Relying on the landmark ruling of the Supreme Court in M/s Modern Insulators Ltd. v. Oriental Insurance Co. Ltd. (2000) 2 SCC 734, the State Commission reiterated that an insurer cannot derive advantage from restrictive terms that were never communicated to the insured. The Bench noted that a consumer must be given a fair opportunity to understand the contractual limitations governing the risk before entering into the contract and paying substantial consideration.
The Commission specifically turned down the insurer's contention that the District Commission had rewritten the policy terms by expanding the defined-benefit coverage to an unlisted disease. The Commission observed that there is a cardinal legal distinction between enforcing an established contract and precluding an insurer from raising uncommunicated exclusionary terms as an afterthought to evade its statutory and contractual obligations.
Insurer cannot circumvent liability when it fails to conduct due diligence and pre-policy medical evaluation
The Bench further found fault with the insurer for issuing the coverage and receiving a premium of ₹1,37,000/- without conducting any preliminary medical evaluation of the proposer. Placing reliance on SBI General Insurance Company Limited v. Balwinder Singh Jolly, the Commission observed that an insurer that fails to exercise due diligence at the stage of risk inception cannot transfer the adverse consequences of its omission onto the consumer.
The State Commission firmly distinguished the precedents cited by the insurer, clarifying that while contractual terms ordinarily bind the parties, such principles apply strictly to conditions that have been duly proved as communicated and accepted, rather than undisclosed policy schedules.
Affirming the order of the District Commission, the State Commission held that the repudiation constituted both a deficiency in service and an unfair trade practice. Consequently, the Commission dismissed the appeal, sustaining the direction issued against the insurer to pay ₹18,00,000/- with 6% annual interest from the repudiation date alongside ₹20,000/- in compensation and litigation costs.
Date of Decision: October 29, 2026