-
by sayum
01 October 2026 8:21 AM







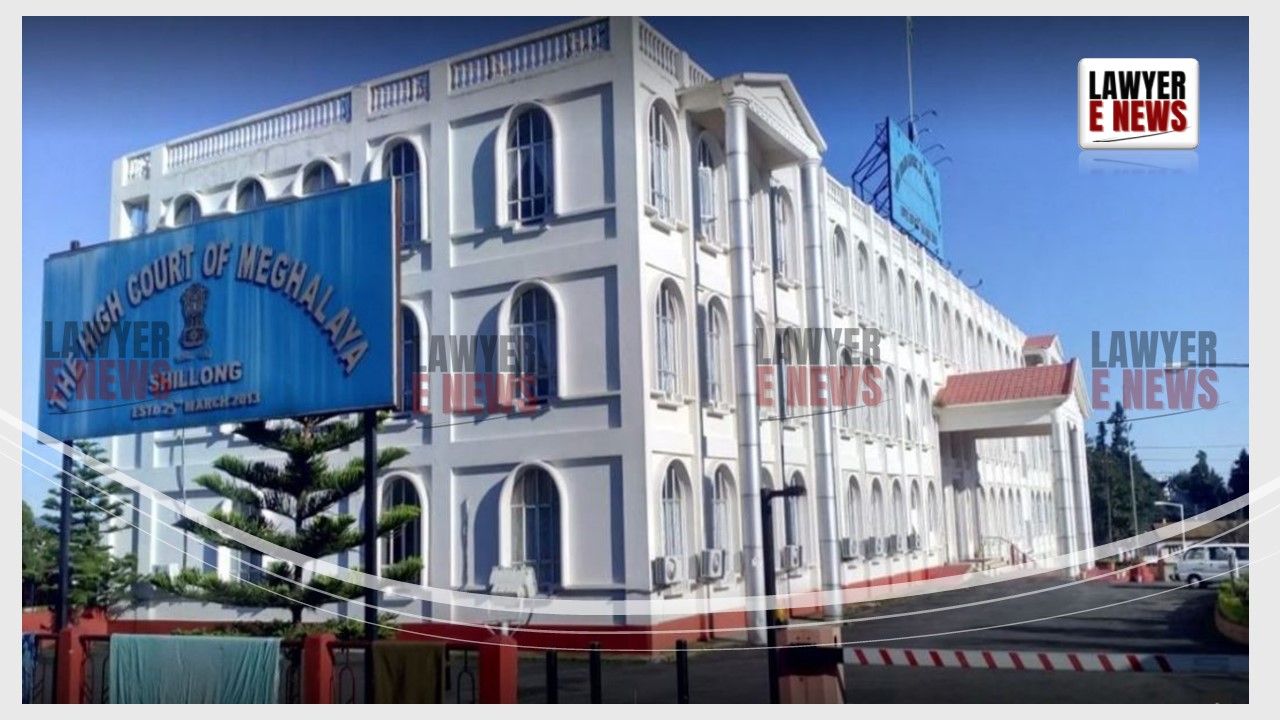
Principal Commissioner’s reassessment order under Section 263 of the Income Tax Act, 1961, overturned, affirming the company’s consistent use of the hybrid accounting method.
The Meghalaya High Court has dismissed the appeal by the Principal Commissioner of Income Tax, Shillong, against the decision of the Income Tax Appellate Tribunal (ITAT), Kolkata-Guwahati “e-Court,” which upheld the use of the hybrid system of accounting by M/s North Eastern Electric Power Corporation Limited (NEEPCO). The bench, comprising Chief Justice S. Vaidyanathan and Justice W. Diengdoh, emphasized the legitimacy of the hybrid method under certain conditions and reiterated the precedence of real income over hypothetical income for taxation purposes.
The case revolves around the assessment year 2014-2015, during which NEEPCO adopted a hybrid system of accounting, combining cash basis and accrual basis methods. The Principal Commissioner of Income Tax, Shillong, challenged this method, arguing it contravened Section 145 of the Income Tax Act, 1961. The original assessment was set aside under Section 263, leading to a reassessment that increased the company’s taxable income significantly. The ITAT quashed the revisionary proceedings under Section 263, stating that the reassessment was erroneous and prejudicial to the revenue’s interests, prompting the appeal to the High Court.
The High Court upheld the ITAT’s decision, affirming that the hybrid system of accounting, while generally uncommon, could be permissible under specific circumstances. The court noted that NEEPCO had consistently used this method for calculating interest on debtors, aligning with directives from the Ministry of Power and judicial precedents.
The court emphasized the distinction between real and hypothetical income, stating, “Income tax is fundamentally a levy on income, and hypothetical income that may or may not materialize should not be subject to tax merely because of an entry in the accounts.” This principle was supported by previous rulings from the Punjab and Haryana High Court and the Supreme Court.
The judgment reiterated the importance of consistency in accounting practices, especially in the absence of material changes in circumstances. “In several assessment years, the Revenue accepted the Tribunal’s order in favor of the assessee, and there is no reason to deviate from this established practice,” the court remarked.
The court’s decision was heavily influenced by judicial precedents which highlighted the need for real income to be the basis for taxation. It quoted, “The Supreme Court in Commissioner of Income Tax vs. Shoorji Vallabhdas and Co. [1962] held that if income does not result at all, there cannot be a tax, even though in book-keeping, an entry is made about a hypothetical income.” The court also pointed out that similar cases, such as those involving Dakshin Haryana Bijli Vitran Nigam Ltd., had consistently ruled in favor of the hybrid accounting method when aligned with practical and realistic financial practices.
Chief Justice S. Vaidyanathan remarked, “The adoption of the hybrid accounting method by NEEPCO is justified and consistent with directives from the Ministry of Power. The re-assessment order based on the Principal Commissioner’s revision was rightly quashed by the ITAT as it failed to meet the necessary legal standards.”
The Meghalaya High Court’s dismissal of the appeal reaffirms the judiciary’s stance on the hybrid system of accounting and the importance of taxing real, not hypothetical, income. This decision not only upholds the ITAT’s order but also sets a precedent for future cases involving similar accounting practices. By reinforcing the principles of consistent and practical financial practices, the judgment provides clarity and stability for companies adopting hybrid accounting methods.
Date of Decision: July 8, 2024
Pr. Commissioner of Income Tax, Shillong vs. M/s North Eastern Electric Power Corporation Limited