-
by sayum
13 October 2026 6:59 AM


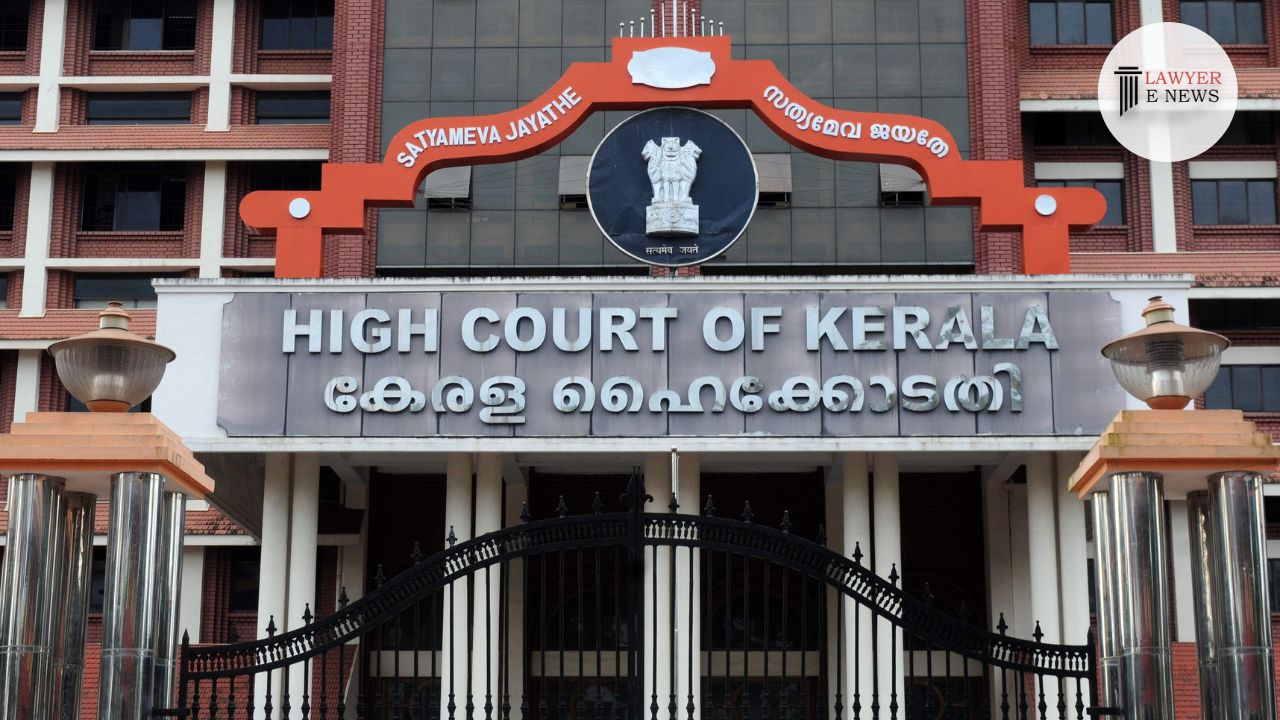
The Kerala High Court in a significant decision has ruled that the benefits of the GST Amnesty Scheme should extend to taxpayers who had filed their GSTR-9 and GSTR-9C returns before the commencement of the scheme. The court held that the late fee demands for the belated filing of GSTR-9C are unjust and unsustainable.
Facts and Issues Arising in the Judgement: The batch of writ petitions involved common questions of fact and law, focusing on the interpretation and applicability of late fees for belated filing of annual GST returns in FORM GSTR-9 and reconciliation statements in FORM GSTR-9C. Petitioners had filed GSTR-9 returns belatedly and paid late fees as mandated by Section 47 of the CGST/SGST Acts. A contention arose regarding the applicability of the GST Amnesty Scheme to these petitioners, who had filed their returns before the scheme’s introduction.
GST Amnesty Scheme’s Applicability: The court observed that the scheme was intended to reduce compliance burdens and legal disputes, stating, “GST Amnesty Scheme aimed at reducing compliance burden and legal disputes – Applicable to taxpayers who filed GSTR-9 belatedly before commencement of scheme.”
Unsustainability of Late Fee Demands: The court held that the late fee demands for the belated filing of GSTR-9C were unjust and unsustainable. It was noted that “Late fee demands for belated filing of GSTR-9C held unjust and unsustainable.”
Directions on Late Fee Collection: The court issued directions to cease the collection of late fees for the delay in filing GSTR-9C, subject to the non-refundability of any late fee already paid over Rs. 10,000.
Non-Refundability of Paid Late Fees: While allowing the writ petitions, the court clarified that petitioners are not entitled to a refund of the late fee already paid over Rs. 10,000.
Decision: The writ petitions were allowed. The court directed the cessation of notices seeking late fee for the delay in filing GSTR-9C, provided that any late fee already paid over Rs. 10,000 will not be refundable.
Date of Decision: 9th April 2024
Anishia Chandrakanth vs Superintendent of Central Tax