-
by Lawyer IT
16 September 2026 1:41 PM







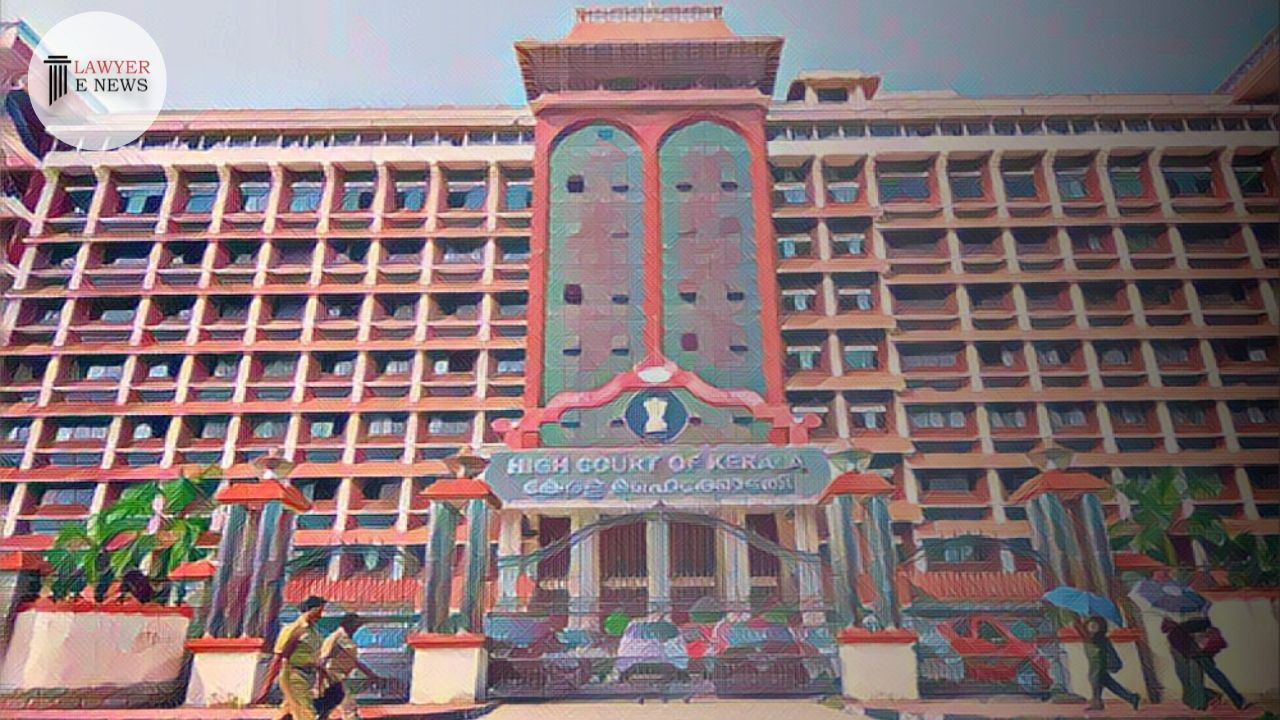
High Court dismisses Equity Intelligence's appeal, emphasizing the importance of timely appeals and procedural adherence in tax assessments.
The Kerala High Court, in a significant ruling, dismissed the appeal filed by Equity Intelligence India Pvt. Ltd., upholding the decision of the Income Tax Department to treat profits from the sale of shares as business income rather than capital gains for the assessment years 2006-2007 and 2008-2009. The court emphasized the necessity for timely appeals and noted the statutory limitations that prevented a re-assessment of previous years' returns.
Equity Intelligence India Pvt. Ltd., a SEBI-registered portfolio manager, filed returns declaring profits from share sales as capital gains for the assessment years 2004-2005 and 2005-2006, which were accepted by the Department without scrutiny. However, for the assessment years 2006-2007 and 2008-2009, the Department re-opened and re-assessed these returns, classifying the profits as business income. Conversely, the appellant declared losses from share transactions for the years 2007-2008 and 2009-2010, which were initially accepted as capital losses.
The appellant sought to revise these assessments to ensure consistent tax treatment by filing revision petitions to treat the losses as business losses, allowing them to carry forward these losses for future assessments. However, these petitions were rejected by the revision authority due to the delay and the contention that Section 143(1) intimation orders are not subject to revision under Section 264 of the Income Tax Act.
Delay in Filing Revision Petitions: The court noted that the appellant did not promptly file the revision petitions after the assessment orders for 2006-2007 and 2008-2009 were issued. The delay was attributed to the appellant's pursuit of appeals against these orders up to the High Court, which ultimately did not rule in their favor. The court agreed with the revision authority’s decision to reject the petitions based on this delay.
Uniformity and Fairness in Taxation: Justice A.K. Jayasankaran Nambiar remarked, "While uniformity and fairness in taxation are critical, these principles cannot override statutory limitations and procedural delays." The court recognized the appellant's argument for consistent tax treatment but highlighted that the Department's inability to re-assess previous years' returns due to statutory limitations must also be considered.
Statutory Limitations: The court underscored that the Department could not reopen the assessments for 2004-2005 and 2005-2006 due to the expiration of the statutory period. Therefore, allowing the appellant to revise their assessments for 2007-2008 and 2009-2010 would create an unfair advantage, as the Department was similarly restricted by statutory limitations.
The judgment highlighted the importance of adhering to statutory time frames and the principles governing the revision of assessments under the Income Tax Act. The court emphasized that procedural delays by the appellant could not justify revisiting concluded assessments, especially when the Department was equally bound by statutory limitations.
Justice Nambiar observed, "To condone the delay and permit the appellant to re-visit the concluded assessment would tantamount to conferring an unfair advantage to the appellant whilst denying such an advantage to the revenue."
The dismissal of Equity Intelligence India Pvt. Ltd.'s appeal by the Kerala High Court reaffirms the importance of timely action in tax-related matters and underscores the limitations imposed by statutory provisions. This decision reinforces the legal framework for assessing business income and capital gains, ensuring that both taxpayers and tax authorities adhere to established procedural norms.
Date of Decision: June 14, 2024
Equity Intelligence India Pvt. Ltd. v. Principal Commissioner of Income Tax & Anr.