-
by sayum
27 October 2026 2:43 PM


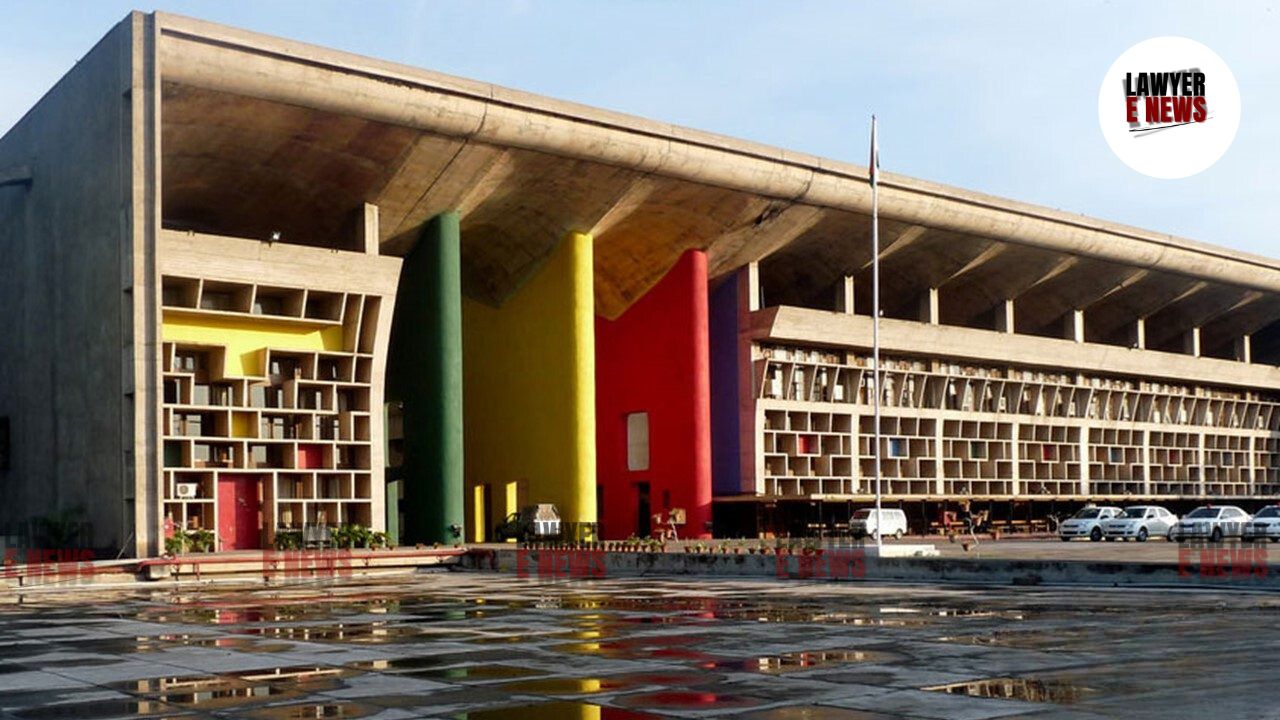
"For determining market value of a tract of land, based on sale consideration of a small piece of land, cut is imposed on account of any of two or both reasons i.e. cost of development and market value of small piece of land vis-à-vis a tract of land." Punjab and Haryana High Court, in a significant ruling, held that standard deductions or "cuts" for development charges cannot be mechanically applied when determining compensation for small commercial plots using sale exemplars of similarly small dimensions.
A single bench of Justice Jagmohan Bansal observed that a cut is primarily warranted when evaluating a large contiguous tract of land based on the sale consideration of a significantly smaller piece of land.
The case arose from the state government's June 1999 notification acquiring 4 Kanal 8 Marla of land in Village Bhainsa Tibba to provide facilities for devotees of the Shri Mata Mansa Devi Shrine Board. The Reference Court had previously assessed the market value at ₹576 per square yard by applying a 50% cut to the base value of ₹1,151, relying on a parallel acquisition of 56 acres of agricultural land. The appellant-landowners approached the High Court seeking an enhancement, arguing that their small commercial plots adjoining the temple did not warrant the same 50% deduction applied to massive agricultural tracts.
The primary question before the court was whether a 50% development cut should be imposed on the market value of acquired land when the acquired parcels are small commercial plots and the relied-upon sale exemplar is of a comparable small size.
Rationale Behind Imposing Development Cuts
The court began by explaining the foundational jurisprudence behind applying deductions to sale exemplars in land acquisition matters. It noted that the value of a developed plot intrinsically includes the cost of infrastructure such as roads, electricity, water, and sewage facilities. Therefore, equating a large undeveloped chunk of land with a small developed plot requires a balancing deduction to account for development costs.
"It is a matter of knowledge that ordinarily a small piece of land fetches more value than a big contiguous piece. Thus, value of a big chunk of land cannot be determined based on sale consideration of a small piece of land," the bench observed.
No Mechanical Application Of Deductions
Relying on a catena of Supreme Court judgments, including Haridwar Development Authority v. Raghubir Singh and Haryana State Agricultural Market Board v. Krishan Kumar, the High Court emphasized that the deduction on account of development charges must be considered strictly within the peculiar facts and circumstances of each individual case. The underlying purpose of the acquisition is also a relevant factor.
The court noted that while the apex court has "permitted deduction for development cost ranging from 20% to 75% of price of small flats," such deductions cannot be invoked blindly without assessing the size and nature of the acquired land relative to the exemplar document.
Parameters For Determining Market Value
Formulating a comprehensive framework for reference courts, Justice Bansal outlined distinct parameters to be kept in mind while determining the value of acquired land. The court stressed that while Collector rates should be considered, they must not be mechanically applied, and sale considerations of acquired land should always be preferred over other lands irrespective of their location.
Among the guidelines, the bench specified that "If sale consideration of acquired land is not available, sale consideration of nearest land possessing advantages should be considered. The principle should be lesser the distance more the preference."
Commercial Nature Of The Acquired Land
Applying these principles to the facts at hand, the court differentiated the appellants' lands from the 56 acres of agricultural land acquired under a parallel notification on the exact same date. The bench observed that the land in question was situated immediately adjoining the temple and was divided into very small parcels ranging from one to three marlas, legally owned by more than fifty individuals.
Emphasizing the commercial utility of these tiny parcels, the court noted, "Size of land owned by appellants vindicates their stand that these plots were used for commercial purposes i.e. sale of items offered by devotees in the temple... The sole utilization of these plots was for commercial purposes."
Unjustified 50% Cut Set Aside
The High Court found a fundamental flaw in the Reference Court's reliance on previous awards to mechanically impose a 50% cut on the present landowners. It reasoned that in the previous litigation, a heavy cut was justified because 56 acres of agricultural land were being valued based on a mere 12-marla sale deed. However, the present appellants already owned micro-parcels, rendering the deduction completely illogical.
"Case of appellants is other way round. The appellants were owners of small pieces of land and total land acquired was 4 Kanal 8 Marla. They are justified in claiming that no cut should be imposed while determining value of their plots," the bench emphatically ruled.
Concluding the judgment, the High Court allowed the appeals filed by the landowners and set aside the 50% cut imposed by the Reference Court. The market value of the commercial plots was definitively assessed at the unreduced rate of ₹1,151 per square yard, alongside all permissible statutory benefits under the Land Acquisition Act, 1894. Consequently, the connected appeals filed by the Shri Mata Mansa Devi Shrine Board were dismissed.
Date of Decision: 14 July 2026