-
by sayum
05 October 2026 9:18 AM







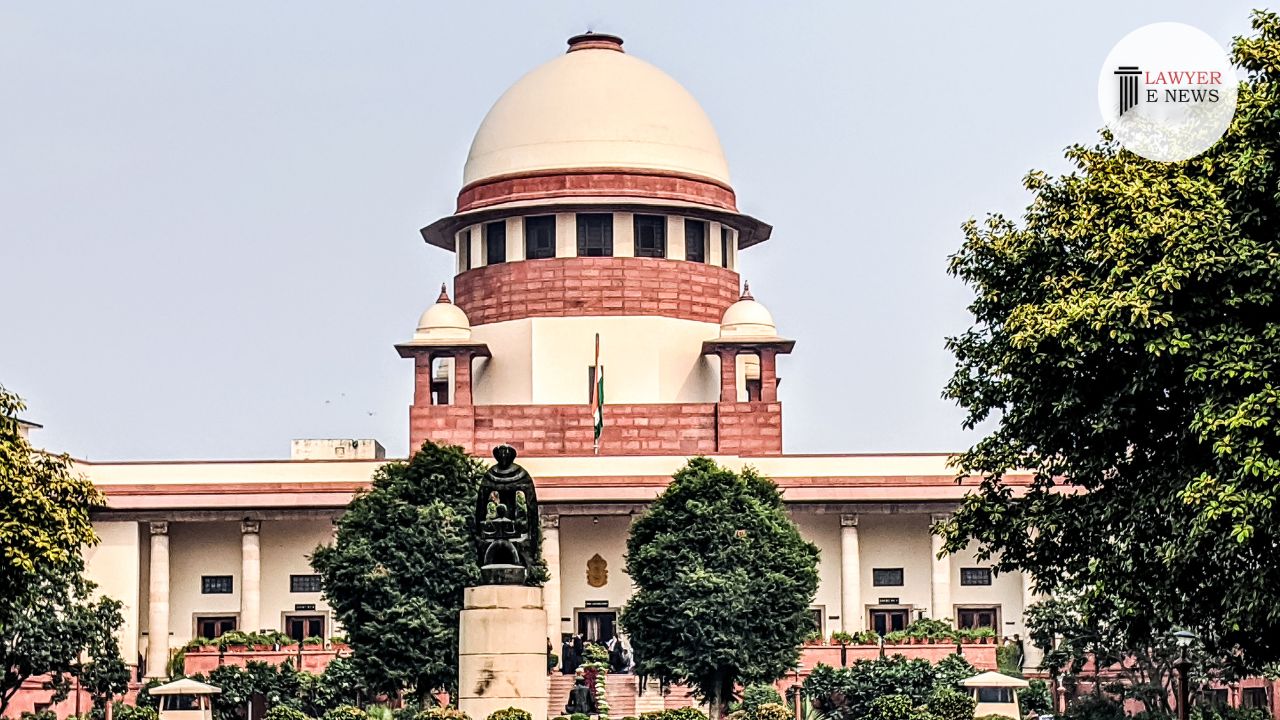
In a landmark judgment that clarifies the tax implications of hiring vehicles and cranes, the Supreme Court of India has provided substantial clarity on the distinction between 'transfer of the right to use' goods and the provision of services. The apex court's decision in the Civil Appeal No.3548 of 2017, involving M/s. K.P. Mozika and Oil and Natural Gas Corporation Ltd. & Others, will have significant repercussions in the realm of service and sales taxation.
Justice Abhay S. Oka, while delivering the judgment, emphasized the essence of the legal interpretation in these cases: "The transaction can be either of transfer of right to use the goods or granting mere permission to use the goods without transfer of the right to use the goods."
The group of appeals under consideration primarily concerned the liability to pay tax under the Assam General Sales Tax Act, 1993, and the Assam Value Added Tax Act, 2003. The contracts in question involved agreements for the provision of various types of motor vehicles and cranes to ONGC and IOCL.
A critical aspect of the judgment revolved around interpreting whether these contracts constituted a transfer of the right to use goods, which would be taxable under the Sales Tax Act or the VAT Act. The Supreme Court meticulously analyzed the agreements' terms and concluded that these were not transfers of rights but mere services, thereby not attracting sales tax or VAT.
In a significant observation, the court noted, "To decide the controversy...the contract will be covered by sub-clause (
(d) of Clause 29A of Article 366, provided all the five conditions laid down are fulfilled."
This decision is a pivotal moment in the ongoing debate over
the taxation of such transactions. It delineates the fine line between a service contract and a contract that involves the transfer of the right to use goods. The court's ruling essentially pivots on the degree of control, possession, and liability retained by the service provider in the contract.
The apex court's judgment has far-reaching implications, particularly for businesses engaging in similar contracts and the taxation authorities. It clarifies the applicable tax regime, potentially impacting the financial planning and contractual strategies of companies in this sector.
The Supreme Court has thus set a precedent that will guide future cases involving similar contractual arrangements. Businesses and tax practitioners alike are expected to closely analyze this judgment for its broader implications on service contracts and the associated tax liabilities.
Supreme Court in Civil Appeal No.3548 of 2017 offers a clear interpretative framework for distinguishing between a service provision and a transfer of the right to use, thereby bringing much-needed clarity to this complex area of tax law.
Date of Decision: 9th January 2024
M/s. K.P. Mozika VS Oil and Natural Gas Corporation Ltd. & Ors