-
by sayum
15 September 2026 7:25 AM







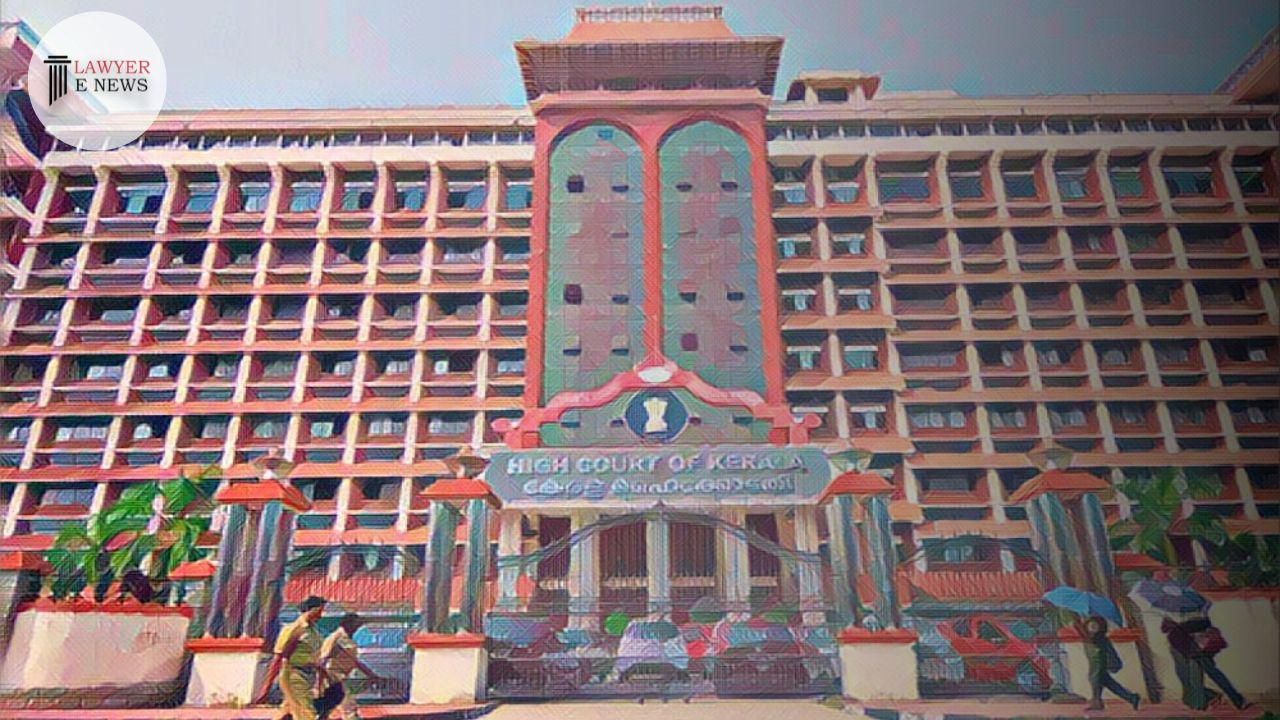
In a significant ruling, the Kerala High Court has held that consideration received for the relinquishment of trusteeship cannot be considered as a capital receipt for tax purposes. The judgment delivered by a Division Bench consisting of Dr. Justice A.K. Jayasankaran Nambiar and Mr. Justice Syam Kumar V.M. on 3rd April 2024, addressed various contentious issues under the Income Tax Act, 1961, relating to the trustees of Carmel Educational Trust and St. Thomas Education Trust.
The primary legal issue centered around whether the remuneration received for relinquishing trusteeship positions within a trust could be classified as a capital receipt and thus not taxable. The court also deliberated on payments received for construction work and donations to the trust.
The case involved the assessment of income and donations received by trustees for AY 2009-10 to 2011-12. The appellants, the Principal Commissioner of Income Tax, Kochi, challenged the Tribunal’s decision on remuneration and donations received by trustees. The trusts were engaged in educational activities and underwent changes in trusteeship, including payments for relinquishing trusteeship and construction work.
Remuneration for Trusteeship Relinquishment: The court observed that no evidence in the trust deed authorized trustees to relinquish their positions for consideration. It held that such remuneration should be treated as individual income of trustees and assessed under appropriate head. This remuneration cannot be treated as a capital receipt.
Construction Work Compensation: The court found no interference necessary in the Tribunal’s reliance on the audited balance sheet and TDS payments regarding amounts received by trustees for construction work.
Donations to Trust: It was upheld that donations received by St. Thomas Education Trust were not to be considered as income in the hands of individual trustees.
Decision: The appeals (ITA Nos. 54/2020, 55/2020, 56/2020, 68/2020, and 6/2021) concerning construction work compensation and donations were dismissed in favor of the assessee. However, the appeals (ITA Nos. 46/2020, 48/2020, 49/2020, and 51/2020) regarding trusteeship relinquishment remuneration were partly allowed and remanded. ITA No. 47/2020 was allowed by way of remand.
Date of Decision: 3rd April 2024
The Principal Commissioner of Income Tax, (Central), Kochi v. Gracy Babu, Adoor P.O, Pathanamthitta & Others